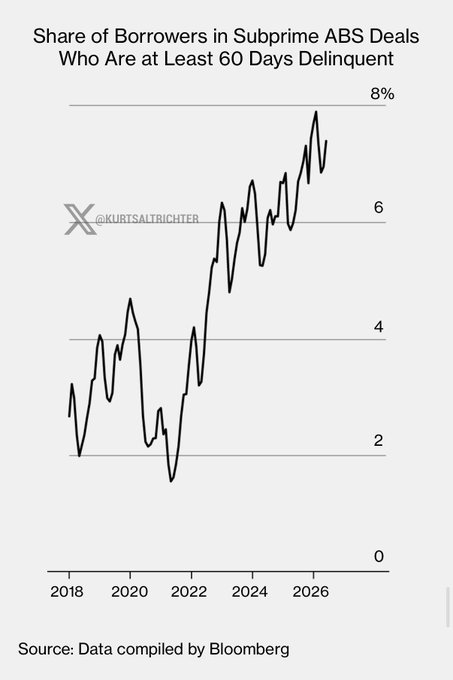
Subprime Auto Delinquencies Hit Record High as Lower-Income Consumers Face Growing Pressure
Financial stress is becoming increasingly visible among lower-income U.S. consumers.
The share of subprime auto borrowers at least 60 days behind on their payments has reportedly climbed to nearly 7%, a record high.
In 2021, that figure was below 2%.
That means roughly 1 in 14 subprime borrowers is now seriously delinquent on a car loan.
Auto payments are often one of the first places financial pressure appears because many households depend on their vehicles for work and have limited room to absorb higher living costs.
The data does not mean the entire U.S. consumer is in recession, but it does suggest significant stress at the lower end of the income and credit spectrum.
That makes auto lenders, subprime ABS markets and discount retailers important areas to watch next.
If delinquencies continue rising while employment remains relatively resilient, it would suggest that high borrowing costs and accumulated inflation are still putting substantial pressure on financially vulnerable households.