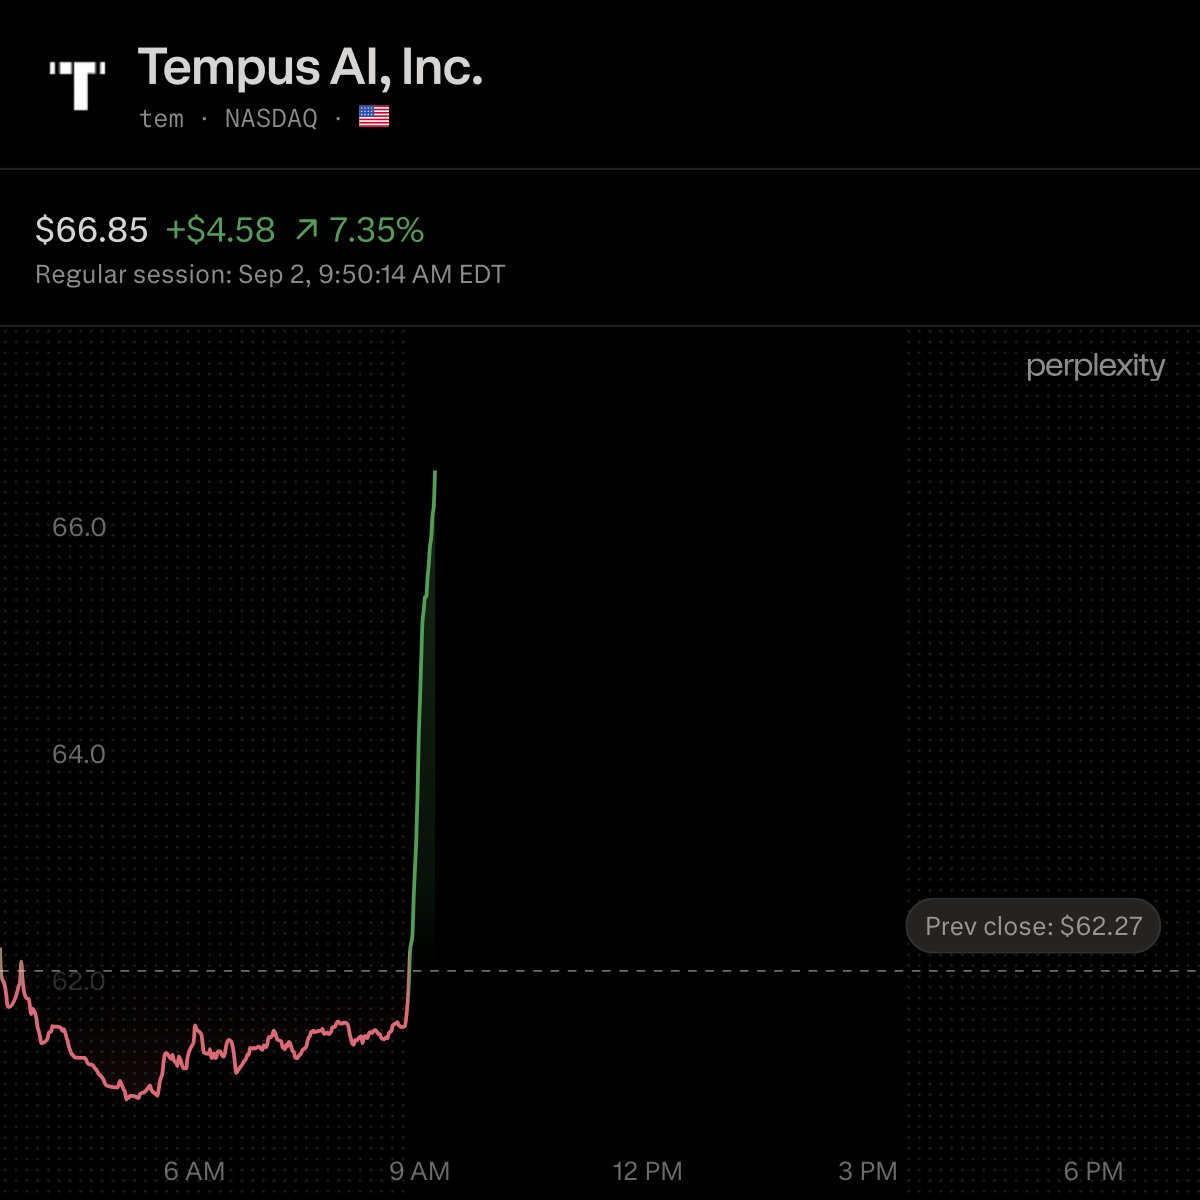
Cantor Fitzgerald Initiates $TEM at Overweight, $80 Price Target
Cantor Fitzgerald analyst Sarah James initiated coverage of $TEM at Overweight with an $80 price target, arguing the stock's upside hinges largely on a single mispricing: the market values its Data & Applications segment like a life-sciences data vendor, even though its growth and margins more closely resemble a platform business.
James noted that while Tempus' diagnostics segment trades in line with true peers such as BLLN, CAI, GH, NTRA, and NEO at 6.6x 2028 EV/Revenue, the Data & Applications segment does not. She said the market is pricing its 26% growth and 76% gross margin off decelerating, hardware-heavy data vendors like IQV, VEEV, TXG, and CERT at 6.1x, rather than platform peers such as PLTR, SNOW, DDOG, and RDDT at 11.7x — a group she believes better matches Tempus' actual growth and margin profile.
Combined with diversified exposure to biopharma R&D, provider adoption, and five underappreciated growth levers, Cantor said the risk/reward skews heavily to the upside.