The Power of Simplicity: Why Broad Indexing Continues to Outpace Most Factor Tilts
The debate between passive cap-weighted index investing and active factor strategies (such as quality or value tilts) frequently highlights a humbling reality for active managers: the standard, broad-market index is exceptionally difficult to consistently beat over long horizons.
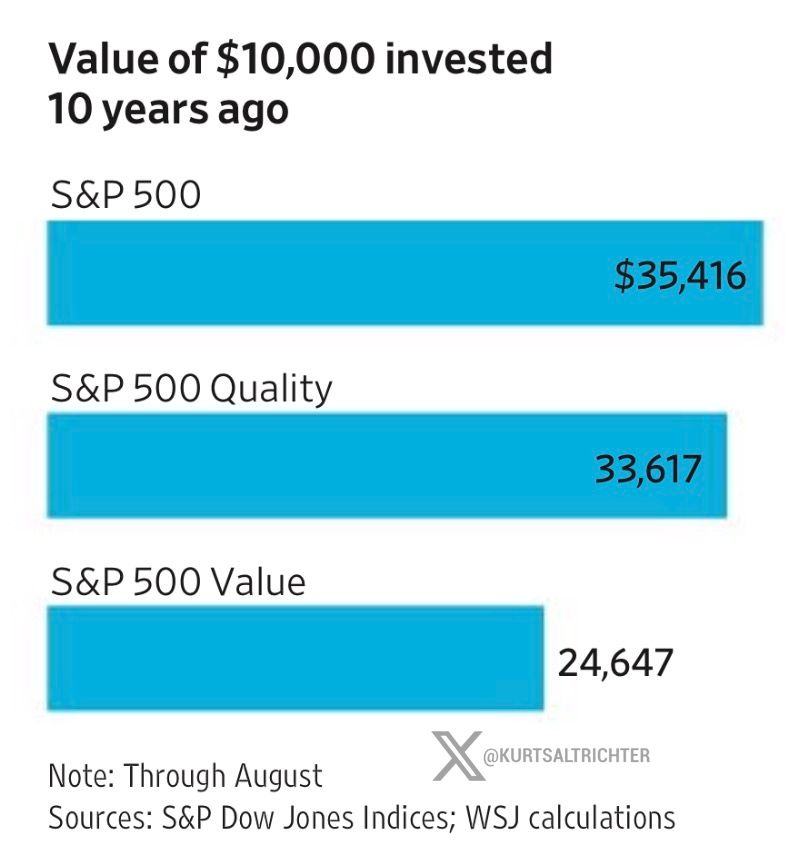
Data comparing a 10-year lookback demonstrates that a $10,000 baseline investment in the broad S&P 500 outgrew comparable multi-factor variations (such as S&P 500 Quality and S&P 500 Value), reinforcing Warren Buffett’s long-standing guidance that low-cost, broad-market accumulation remains an optimal core strategy for the vast majority of long-term investors.