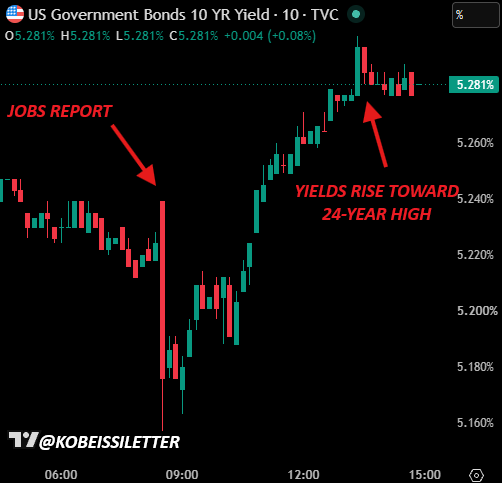
Treasury Yields Rebound Despite Weak September Payrolls and Cooling PCE Print
Long-dated U.S. sovereign debt staged an aggressive intraday reversal, with the 10-year Treasury yield ($TNX) quickly erasing post-data declines within an hour of release despite compounding signs of macroeconomic and labor market cooling.
The bond market's resilience against downward yield momentum highlights several cross-currents:
• Data vs. Duration: Headline September nonfarm payrolls missed consensus estimates alongside a cumulative two-month net downward revision of -60,000 jobs, while PCE deflator metrics printed softer than forecast—conditions that fundamentally favor rate-cut pricing and bond rallies.
• Supply and Term Premium: Reluctance by the benchmark 10-year yield to sustain a move lower signals that heavy sovereign debt issuance, persistent fiscal deficit concerns, and demand for structural term premium are offsetting standard disinflationary flight-to-safety dynamics.
• Policy Decoupling: Market pricing indicates growing tension between front-end rate easing expectations and long-end yield stickiness, limiting the scope of monetary policy relief along the broader curve.