European Long-Term Yields Jump as Fiscal Concerns Keep Building
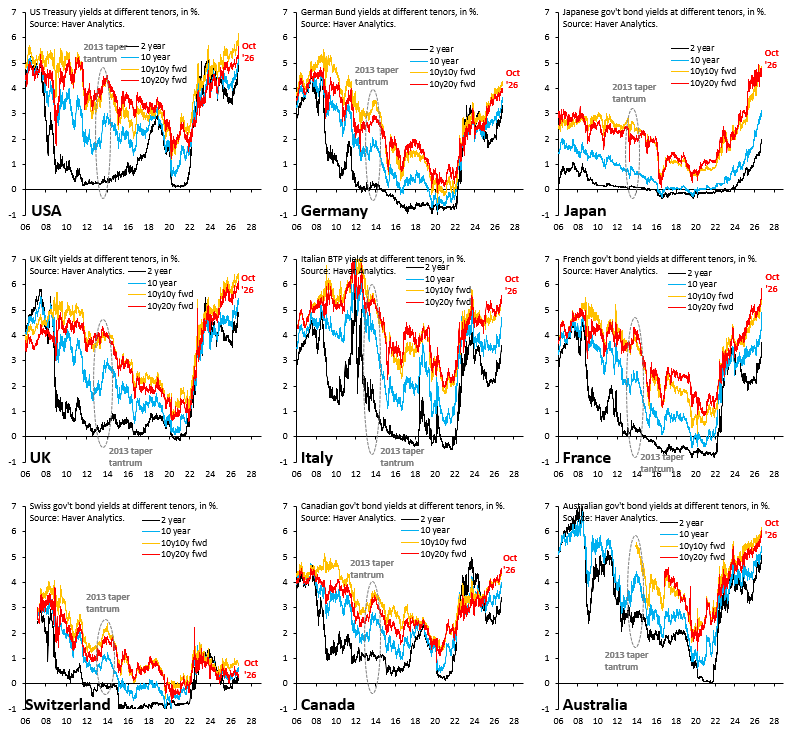
Long-term government yields are moving sharply higher across Europe.
France, Italy and the UK are all seeing significant pressure at the long end of their yield curves, with measures such as 10y10y and 10y20y forward rates rising by more than 10 basis points.
These forward rates reflect where markets expect long-term borrowing costs to sit many years into the future.
The move suggests investors are not simply pricing a temporary central-bank cycle.
Instead, markets are increasingly demanding greater compensation for long-term inflation, fiscal and debt-supply risks.
The roots of the selloff stretch back to the massive fiscal expansion that began during COVID, when governments dramatically increased borrowing to support their economies.
Years later, deficits remain elevated while refinancing needs and debt-service costs continue rising.
That combination is putting persistent upward pressure on long-term yields even as expectations for near-term monetary policy fluctuate.
The broader signal is that bond markets are increasingly questioning whether the post-COVID fiscal expansion was temporary or the beginning of a structurally higher borrowing regime.