Structural Shale Depletion and Upstream CapEx Retrenchment Point to Sustained Oil Price Pressures
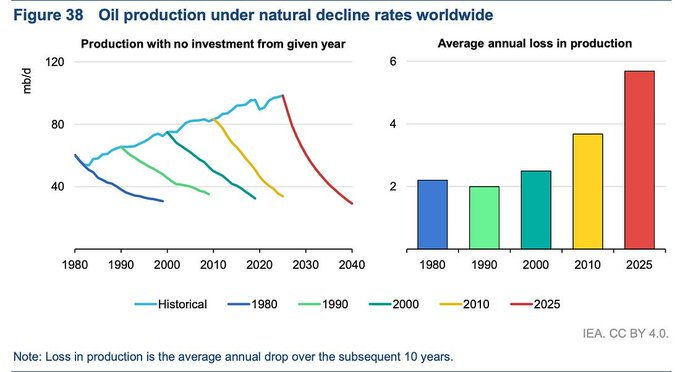
While immediate financial headlines remain centered on near-term geopolitical bottlenecks, structural supply dynamics indicate compounding long-term vulnerabilities across global energy markets. Rapid depletion rates in U.S. shale basins have effectively doubled global upstream natural decline rates, accelerating the treadmill required to sustain baseline capacity.
To offset existing field depletion and keep aggregate output flat, the global energy complex must replace volume equivalent to Iraq's entire production—the world's fourth-largest oil producer—every single year.
Compounding this decline curve, ongoing regional conflict and heightened uncertainty are restraining long-term upstream capital expenditures (CapEx) rather than catalyzing new exploration. With upstream reinvestment failing to offset underlying legacy field exhaustion, analysts warn that long-term crude pricing faces sustained structural upside, regardless of near-term shipping transit through the Strait of Hormuz.