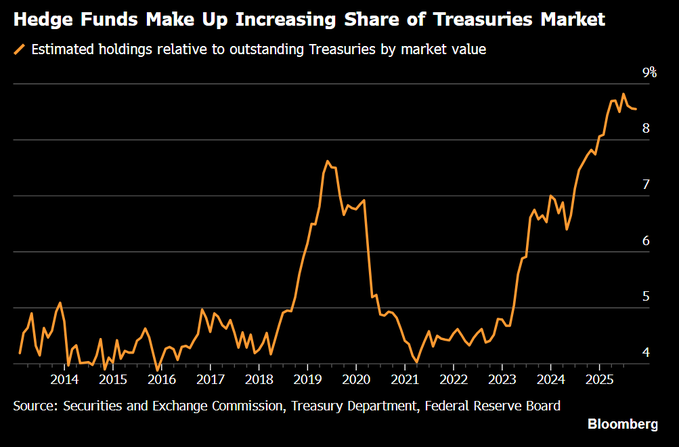
Hedge Funds Amass Record ~8.5% Share of U.S. Treasury Market Driven by Basis Trade Leverage
Hedge funds have accumulated a historic share of the U.S. Treasury market, with estimated holdings climbing toward 8.5% to 9% of total outstanding marketable debt by market value, according to regulatory data compiled by Bloomberg from the SEC, Treasury Department, and Federal Reserve Board[cite: 1]. The allocation surpasses the prior cycle peak of roughly 7.3% recorded in late 2019, reflecting an aggressive post-2023 expansion from cyclical lows near 4%[cite: 1].
The dramatic ramp in hedge fund positioning underscores their growing role as the primary marginal buyers absorbing surging federal deficit issuance, largely replacing traditional foreign central bank demand. However, the vast majority of this cash Treasury exposure is tied to the leveraged "basis trade"—an arbitrage strategy where funds buy spot Treasuries financed through short-term repo borrowing while shorting corresponding Treasury futures contracts to harvest small price misalignments.
While the trade provides essential liquidity and helps cap long-term borrowing costs, the concentration of leveraged capital has amplified regulatory concern across the Federal Reserve and SEC. Because positions rely heavily on overnight and short-term repo leverage, any sudden spike in financing costs, volatility expansion, or margin call spiral could force disorderly unwinds reminiscent of the March 2020 Treasury liquidity freeze, accelerating regulatory momentum toward mandatory central clearing for Treasury cash and repo markets.