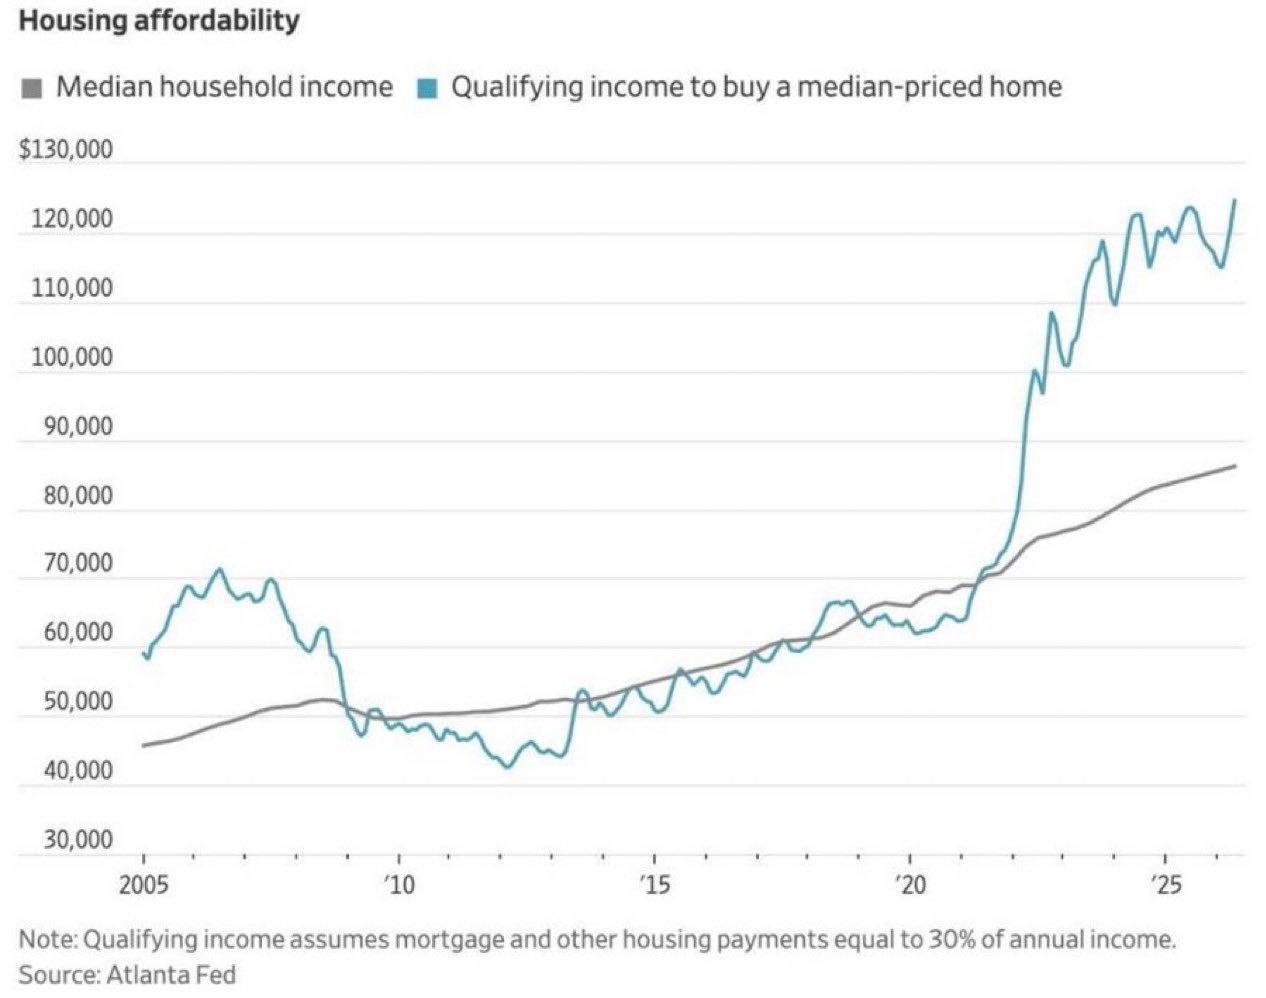
U.S. Housing Affordability Falls to a Record Low
U.S. housing affordability has deteriorated to historically extreme levels.
Home prices remain elevated while mortgage rates are still high, pushing monthly payments far above what buyers faced during the ultra-low-rate period.
The problem is the combination of both variables.
Even if home prices stop rising, financing the same property becomes dramatically more expensive when mortgage rates stay elevated.
At the same time, many existing homeowners are locked into older mortgages at much lower rates, reducing the incentive to sell and keeping housing supply tight.
That creates an unusual market where affordability is extremely weak but home prices remain supported by limited inventory.
Higher insurance, property taxes and maintenance costs are adding another layer of pressure for buyers.
The result is a housing market where the monthly cost of ownership has moved much faster than household incomes.
The key question is what eventually restores affordability: lower mortgage rates, falling home prices, stronger income growth, or some combination of all three.