Cboe Volatility Index ($VIX) Surges 16.6 Points to 35.9—5th-Largest Weekly Jump on Record—Pointing to...
The Cboe Volatility Index ($VIX) surged 16.6 points during the week ending November 20, 2026, closing at 35.9—its highest weekly settlement since April 2025—and recording its fifth-largest weekly point increase on record.
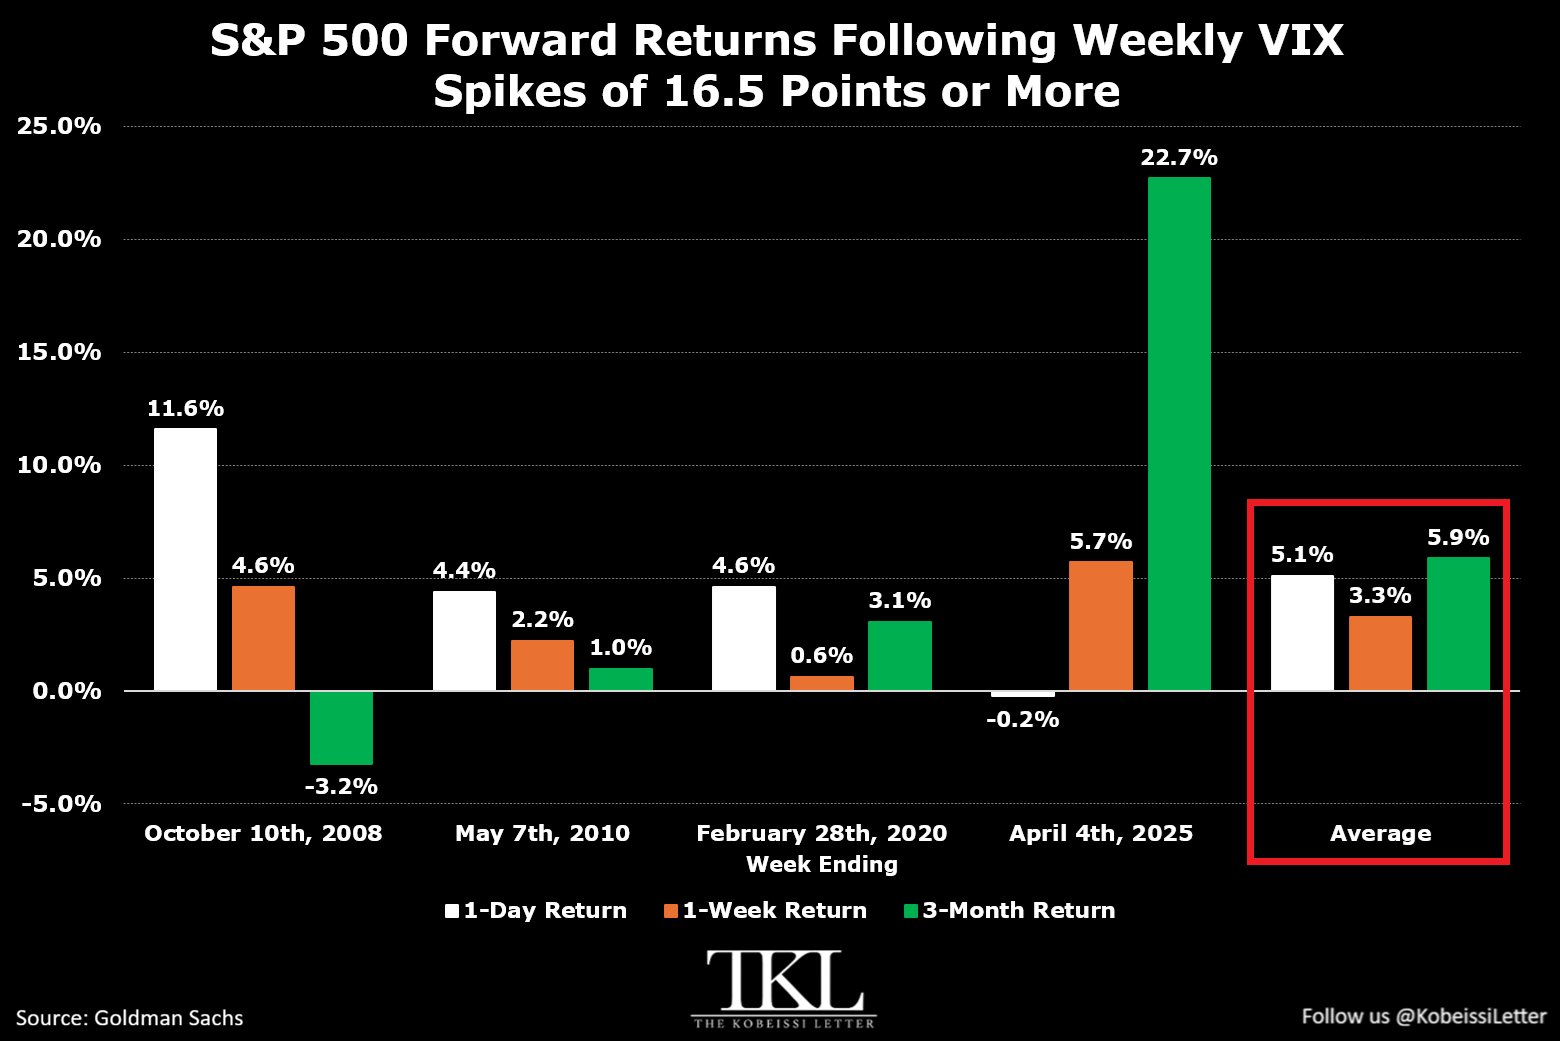
Historical data since 1990 indicates that extreme weekly volatility spikes have frequently preceded short- and medium-term rebounds in the S&P 500 ($SPX) as dip buyers step in:
- Next-Day Performance: Following the four prior weekly $VIX increases of at least 16.5 points since 1990, the S&P 500 rallied an average of 5.1% on the next trading day.
- One-Week Performance: The benchmark index gained an average of 3.3% over the subsequent week, posting positive returns across all four historical instances.
- Three-Month Performance: Over a three-month horizon, the S&P 500 delivered an average return of 5.9%—including a 22.7% rally following the most recent comparable spike during the April 2025 post-tariff market turmoil.